The government has announced Your First Home in England. Explore its expected 2.5% deposit and 20% equity-loan design, and what awaits Budget confirmation.
Your First Home: England's Announced Equity Loan Scheme
Government announcement — 26 September 2026
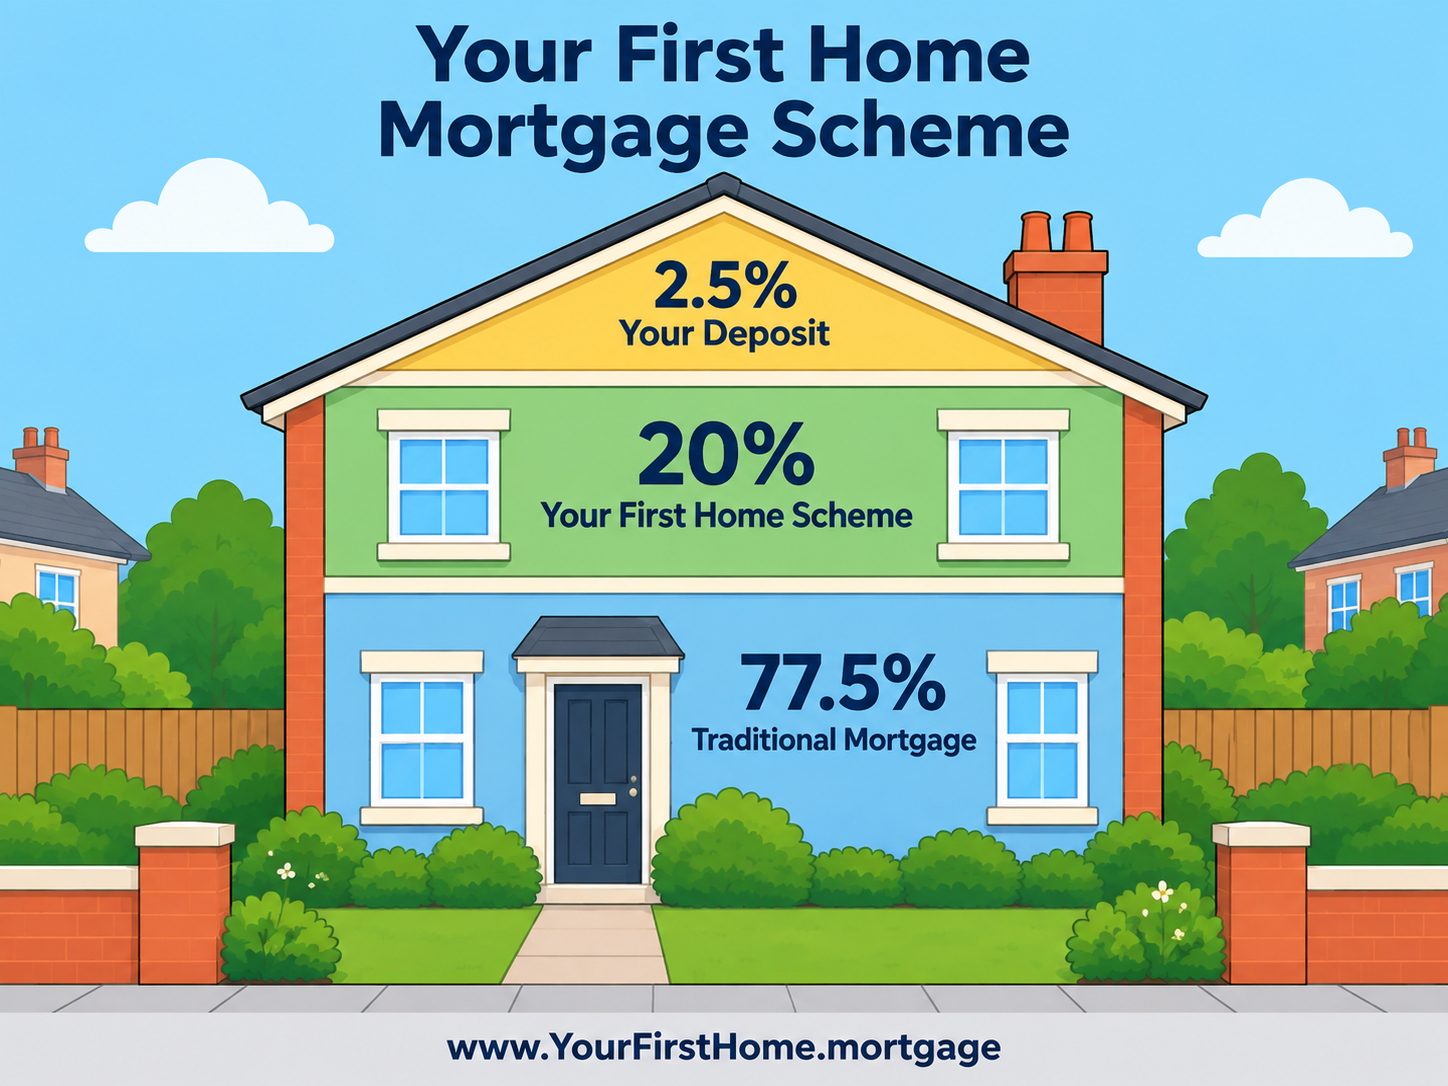
The government has announced Your First Home, a new equity-loan scheme for first-time buyers in England. Its announced outline is expected to support a 2.5% buyer deposit backed by a 20% government-backed equity loan for a new build from a signed-up developer. The scheme is not yet open for applications. Full terms, including income and local property-price cap levels, costs and implementation timings, are due at the Budget next month. Read the Number 10 announcement and the government press release.
A smaller deposit could bring a first home within reach sooner. The government has announced Your First Home for first-time buyers in England, particularly people who cannot rely on family help with a deposit. Here is what the official announcement says about the expected 2.5% buyer deposit and 20% government-backed equity loan, and what still awaits Budget confirmation. This is an announcement, not an operational launch: you cannot apply yet.
What is the Your First Home scheme?
Your First Home is the government's announced equity-loan scheme for eligible first-time buyers in England purchasing a new-build home from a developer signed up to the scheme. The government expects it to support a 2.5% buyer deposit alongside a 20% government-backed equity loan. The equity loan will have an initial interest-free period, but its duration and later charges have not been set out. Developers will be expected to contribute to scheme costs; the Sunday Mirror additionally reports a fee linked to property values, a detail not confirmed in the government press release. Full scheme terms are due at the Budget next month. The scheme is not available for applications today.
This is a different structure from simply borrowing 97.5% of the price as a mortgage. If the announced 20% equity loan applies in full, an illustration for a £250,000 home would be £6,250 buyer deposit + £50,000 equity loan + £193,750 mortgage (before fees and subject to the final rules). The mortgage in that example would be 77.5% LTV, while the buyer would also owe the separate equity loan. The precise costs and repayment terms still need confirmation; an equity loan is not a grant.
The scheme is aimed at first-time buyers in England, especially those who struggle to raise a deposit without help from family. The government says purchases will be new-build homes from signed-up developers, subject to a household-income cap and local property-price caps. The thresholds have not yet been announced and are expected at the Budget. Number 10 says pre-registration is set to open by the end of 2026; this is a target for registering interest, not an open application date or a promise of eligibility. The date when full applications might open remains unknown.
We do not yet know the income or local price-cap levels, whether every co-buyer must be a first-time buyer, any age restriction, which developers or homes will be signed up, lender participation or how applications will be assessed. The reference to helping “young people” does not establish an age limit. A lender would still need to assess income, spending, existing debts, credit and the property before offering a mortgage.
What does a 2.5% deposit mean?
The government expects Your First Home to support a 2.5% buyer deposit: £2,500 for every £100,000 of purchase price. Illustrative figures:
Home price
2.5% buyer deposit
Balance to fund after deposit
£200,000
£5,000
£195,000
£250,000
£6,250
£243,750
£300,000
£7,500
£292,500
The balance is not necessarily the mortgage. Under the announced design, it would be split between an equity loan and a mortgage. At an illustrative 20% equity loan, the £250,000 example would need a £193,750 mortgage, not £243,750. Actual funding shares and eligibility depend on the final terms. You will also need to budget separately for legal work, a survey, moving costs and any applicable taxes and fees. A lower deposit does not remove the need to afford monthly payments or the possibility that property values fall.
Explore the deposit with our LTV calculator
Important: The calculator below starts with a £250,000 property and a £243,750 mortgage, leaving a £6,250 (2.5%) deposit. It shows the arithmetic for a mortgage-only, 97.5% LTV illustration. It does not model the announced equity loan, test Your First Home eligibility, or mean a 97.5% mortgage will be available under this scheme. If an equity loan pays part of the price, the real mortgage could be smaller and the equity loan would be a separate obligation.
Change any value and the other figures will update automatically.
Changing the property value keeps the mortgage amount and recalculates your deposit or equity
and LTV.
Deposit or equity
£
£0£250,000
Mortgage amount
£
£0£250,000
Loan-to-value
97.5%
%
0%100%
No mortgage borrowing needed
With these figures, the property value is fully covered by your deposit or equity. No mortgage
borrowing is required.
Small mortgage amount
Fewer lenders offer mortgages below £25,000, so your options may be limited. Product and legal
fees can also have a greater impact on the overall cost of a smaller mortgage.
Low property value
Fewer lenders offer mortgages on properties valued below £50,000. Minimum property values vary
by lender and property type.
Buying to let?
If this is a buy-to-let purchase, most lenders cap borrowing at 75–80% loan-to-value, with some
specialist options reaching 85%. This cap applies to buy-to-let mortgages only — residential lending
typically extends to 95%.
High-LTV residential mortgage
Residential mortgages above 95% LTV have limited availability and often require a specialist
mortgage product or scheme. Talk to your mortgage adviser about your options.
No deposit or equity buffer
You have no deposit or equity buffer. A fall in the property's value could leave you owing more than
it is worth. No-deposit residential mortgages have limited availability and specific eligibility
requirements. Speak to your mortgage adviser.
Understanding your deposit and LTV illustration
For a property valued at £250,000, the calculator currently shows a £6,250 deposit or equity (2.5%) and a £243,750 mortgage (97.5% LTV). Change the values to explore other purchase prices or deposit amounts.
This is a mortgage-only illustration, not a projection of the Your First Home financing package. The announced scheme is expected to include an equity loan. This calculator cannot add an equity loan to the mix, calculate the cost of repaying one, check lender affordability or confirm that any product is available. The calculator's mortgage-search link shows general mortgage options, not Your First Home products.
Who or what is a first-time buyer?
Generally, a first-time buyer is someone who has never owned a residential property before, but the precise definition depends on the scheme, lender and tax rules. Owning a home abroad, inheriting a share in a property or applying with someone who has owned before can matter. Being young or currently renting does not by itself prove eligibility. Your First Home's own first-time-buyer definition has not been published, so do not assume another scheme's rules will apply unchanged. See our first-time buyer eligibility guide for the wider mortgage checks.
Why could this help first-time buyers?
A 2.5% buyer deposit rather than 5% would halve the headline deposit on the same property: £6,250 instead of £12,500 on a £250,000 home. For buyers without family support, that could shorten the time needed to save. If the announced equity loan covers part of the purchase price, it could reduce the mortgage required compared with a mortgage-only 2.5% deposit purchase. Neither benefit is guaranteed for any particular buyer: eligibility, scheme costs and lender checks still matter.
The scheme also has a housing-supply aim alongside helping first-time buyers: directing support towards new builds could strengthen demand and give builders more confidence to start projects. In The Telegraph's reporting, a Home Builders Federation spokesman said weak demand was constraining construction. That is a reported rationale, not evidence that this scheme will increase the number of homes built.
There are trade-offs. An equity loan can create a separate amount to repay when selling or buying out the government's interest, potentially changing with the home's value depending on the final terms. A small initial cash stake offers a limited buffer if the value falls. New-build availability, regional prices and local caps may also determine whether a suitable home qualifies. Compare the full cost and obligations, not just the minimum cash deposit.
What remains uncertain — and what happens next?
The government says full terms, costs and implementation timelines will be set out at next month's Budget. Number 10 expects pre-registration by the end of 2026, but the scheme has been announced, not launched, and no full application opening date has been confirmed. The Sunday Mirror reports that John Healey is expected to provide further details at the Budget and that the scheme would be funded by reprioritising existing government budgets; these specific details come from press reporting, not the government press release. Further official documents should clarify:
the exact pre-registration process, full application and operational launch dates;
the household-income and local property-price cap levels, any deposit limits and the exact first-time-buyer definition;
which new builds, developers and mortgage lenders participate;
the detailed equity-loan terms, including the interest-free period's duration, later charges, repayment and resale rules;
how affordability and mortgage borrowing are assessed alongside the equity loan; and
whether further buyer protections apply if property values fall.
GOV.UK, 26 September 2026: new first-time buyer scheme to be confirmed at Budget — official announcement of the England new-build scheme, expected 2.5% deposit and 20% government-backed equity loan, initial interest-free period and developer contribution; cap levels, costs and implementation timings remain forthcoming.
Number 10 announcement on X, 26 September 2026 — says the scheme is aimed at buyers without family deposit support and pre-registration is set to open by the end of the year; this is not a full application launch.
Sunday Mirror, 26 September 2026 — secondary reporting on the developer fee linked to property values, John Healey and budget reprioritisation; those details should not be mistaken for published government rules.
The Telegraph, Camilla Turner, 26 September 2026 — reporting on new-build demand and the housing-supply rationale, including the Home Builders Federation spokesman's comments; not evidence of scheme outcomes.
We are your online mortgage broker, offering you the convenience of applying for a mortgage online.
However, we understand that sometimes you may prefer to speak with a human - phone, email or in
person.
We are authorised and regulated by the Financial Conduct Authority (No.
919921). The Financial Conduct Authority does not regulate most Buy to Let mortgages.
Think carefully before securing other debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage.
Our initial consultation is free. If you choose to proceed, we’ll explain any broker fees upfront before you commit.
British Company
Cyborg Finance Limited is registered in England and Wales (No.
12131863) at Bradford Chamber, New Lane, Bradford, BD4 8BX.