A first-time buyer mortgage news hub covering key updates, market themes and what they can mean for your home purchase plans.
First-Time Buyer News
First-time buyer mortgages news
Buying your first home often comes with more questions than answers—especially when mortgage rules, lender criteria and wider economic factors shift over time. This page brings together the themes and updates that tend to matter most for first-time buyers, so you can understand what’s changing and how it may affect your mortgage planning.
Important: Mortgage availability and pricing can change frequently. Any information here is for general awareness and should be considered alongside your own circumstances.
What “news” means for first-time buyers
When people search for first-time buyer mortgage news, they’re usually looking for clarity on topics such as:
- Mortgage rates and product availability (how lenders price risk and manage funding)
- Changes to affordability expectations (how income and outgoings are assessed)
- Deposit and scheme updates (including how support for new-build purchases may work)
- Credit profile considerations (what lenders look for when reviewing applications)
- Regulatory and industry developments (wider changes that can influence mortgage processes)
Because first-time buyers often have less flexibility than experienced borrowers, small changes can have a bigger impact—particularly if you’re near your deposit limit or relying on a specific type of mortgage.
Key themes to watch
1) Interest rate movement and how it affects monthly payments
Even when you’re not changing your plans immediately, rate movements can influence:
- the cost of borrowing
- the size of mortgage you can comfortably afford
- how lenders structure fixed vs variable options
If you’re comparing options, it’s helpful to focus on the full picture: not just the headline rate, but also the term, repayment type and any product features.
2) Affordability assessments and “stress testing”
Lenders assess affordability using more than just your current monthly payment. They may consider:
- your income stability
- existing commitments (credit cards, loans, childcare, etc.)
- how payments could change over time
For first-time buyers, improving your financial picture—such as reducing unsecured debt or ensuring consistent income—can be just as important as shopping around.
3) Deposit expectations and mortgage-to-value (LTV)
Deposit size remains a central factor in what’s available. As LTV changes, lenders may adjust:
- which products they offer
- the pricing they apply
- the level of documentation they require
If you’re working towards a specific deposit target, it can be useful to understand how different deposit levels may affect the mortgage options you’re likely to see.
4) New-build support and scheme availability
For some first-time buyers, support tied to new-build purchases can influence the route to ownership. Scheme details and eligibility can change, and availability may vary by development and lender.
If you’re considering a new-build purchase, it’s worth keeping an eye on how support works in practice and how it may interact with mortgage lending criteria.
5) Credit profile and application readiness
News isn’t always about the market—sometimes it’s about what lenders are paying attention to. Common themes include:
- ensuring your credit file is accurate
- avoiding new credit applications during the buying process
- keeping spending patterns stable
If you’re planning to apply soon, preparation can reduce friction later.
How to use this page alongside your first-time buyer planning
This news hub is designed to complement the rest of your first-time buyer resources. A practical approach is:
- Start with your affordability so you know what you’re aiming for.
- Review the mortgage types and schemes that may be relevant to your deposit and property type.
- Use the latest guidance themes from this page to understand what could affect lender decisions.
- Prepare documents early so you’re not rushed when you find the right property.
For broader first-time buyer guidance, you can also explore the supporting resources in the First-time buyer guides area.
Related first-time buyer resources
- First-time buyer guides: explore the end-to-end process and key topics.
- First-time buyer calculator: estimate borrowing potential and plan your next steps.
- First-time buyer FAQ: clear up common questions about mortgages and the buying journey.
- First-time buyer eligibility: understand how lenders may view different situations.
- First-time buyer case studies: see how different circumstances can shape mortgage journeys.
Next updates
This page is intended to be updated as new themes emerge that are relevant for first-time buyers. If you’re planning to apply for a mortgage, it can be helpful to review updates close to the point you’re ready to submit an application—so your planning reflects the most current market context.
Mortgage Market News
Six-to-three vote to hold at 3.75%
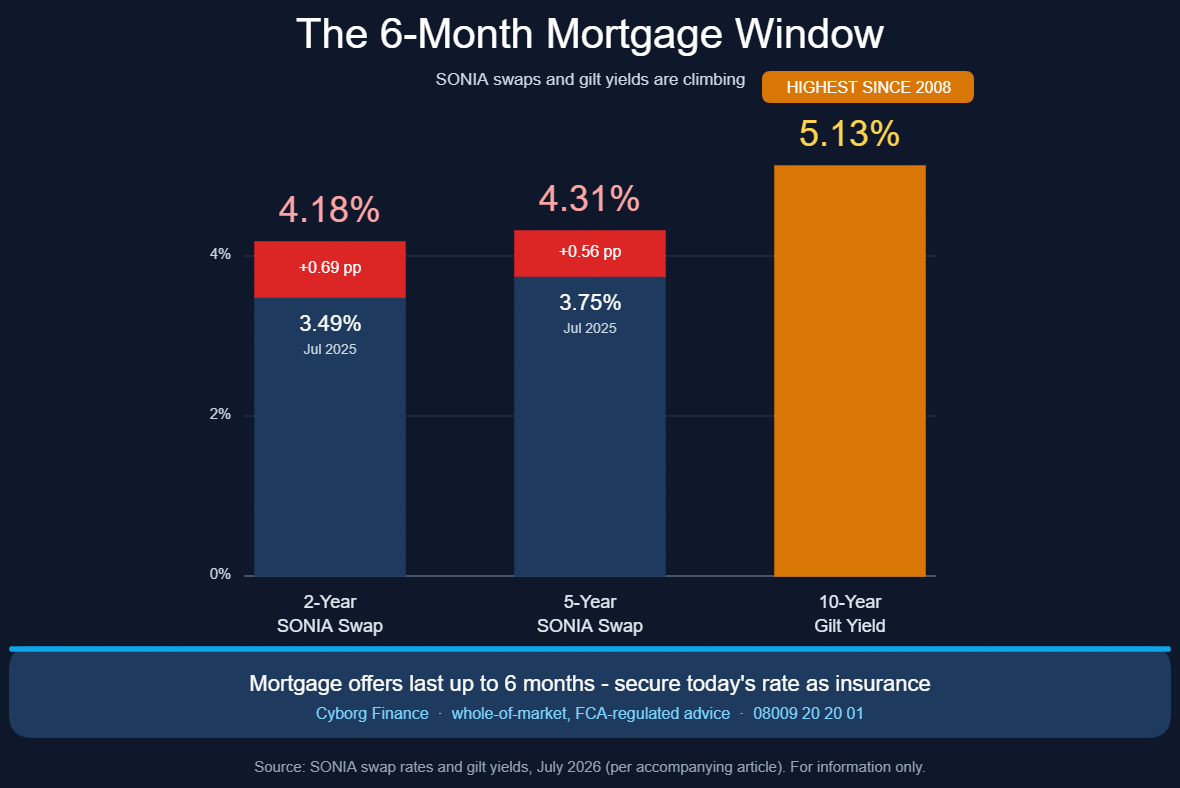
Do not wait until your deal ends and you slip onto your lender's standard variable rate.
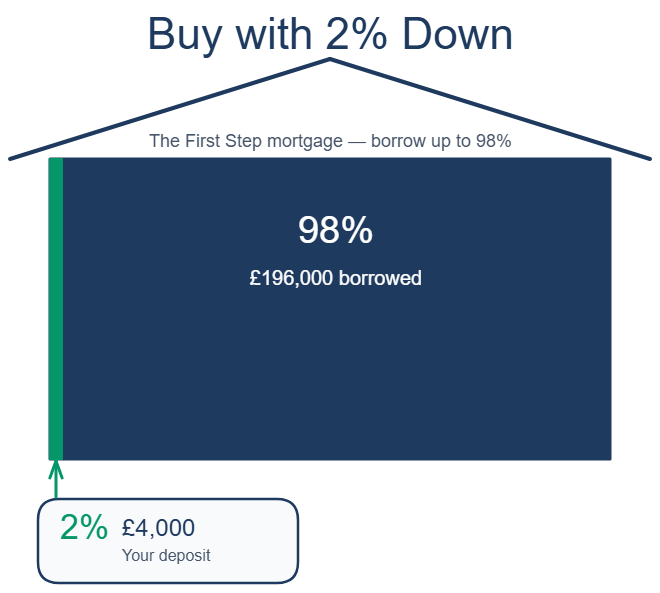
First Step stands out for what it allows. It accepts gifted deposits, lends on new-build houses, and considers self-employed applicants.
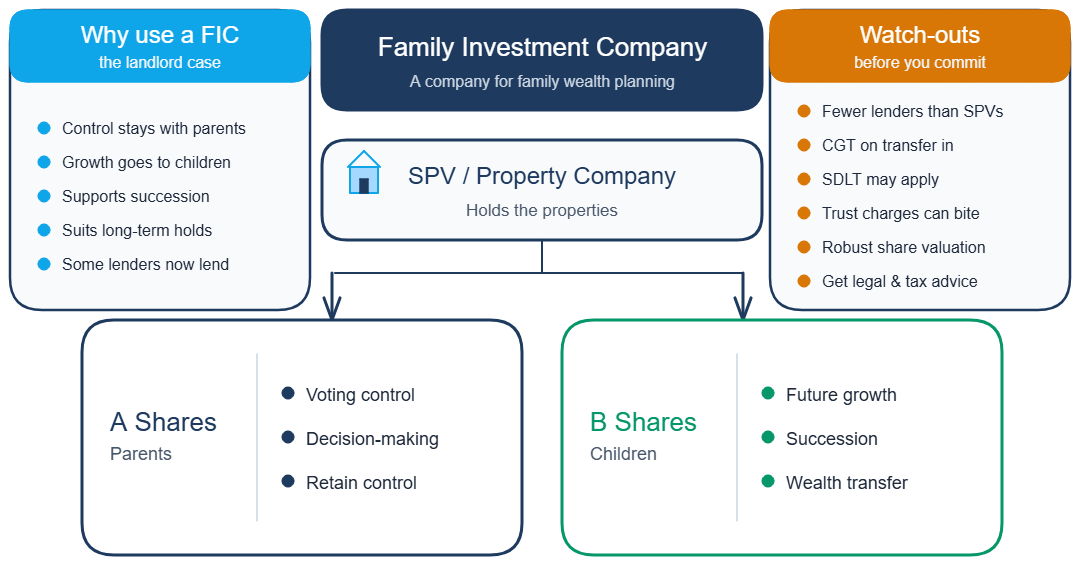
Mortgage Advisers now have lenders who are comfortable with Family Investment Companies (FICs).
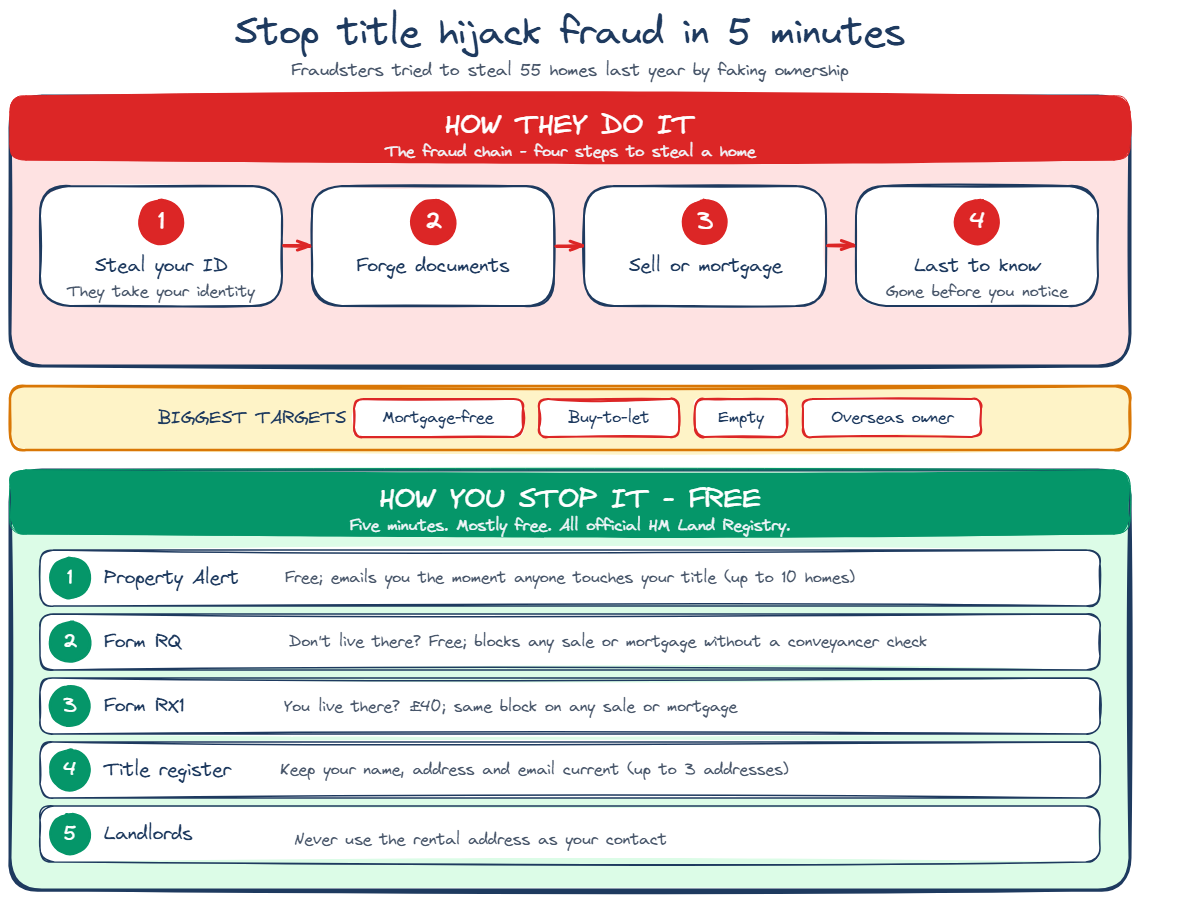
Criminals steal your identity and forge a few documents. They then sell your home, mortgage it, or transfer ownership. AI is making it worse. Forged documents now slip past checks built for an older era of fraud.
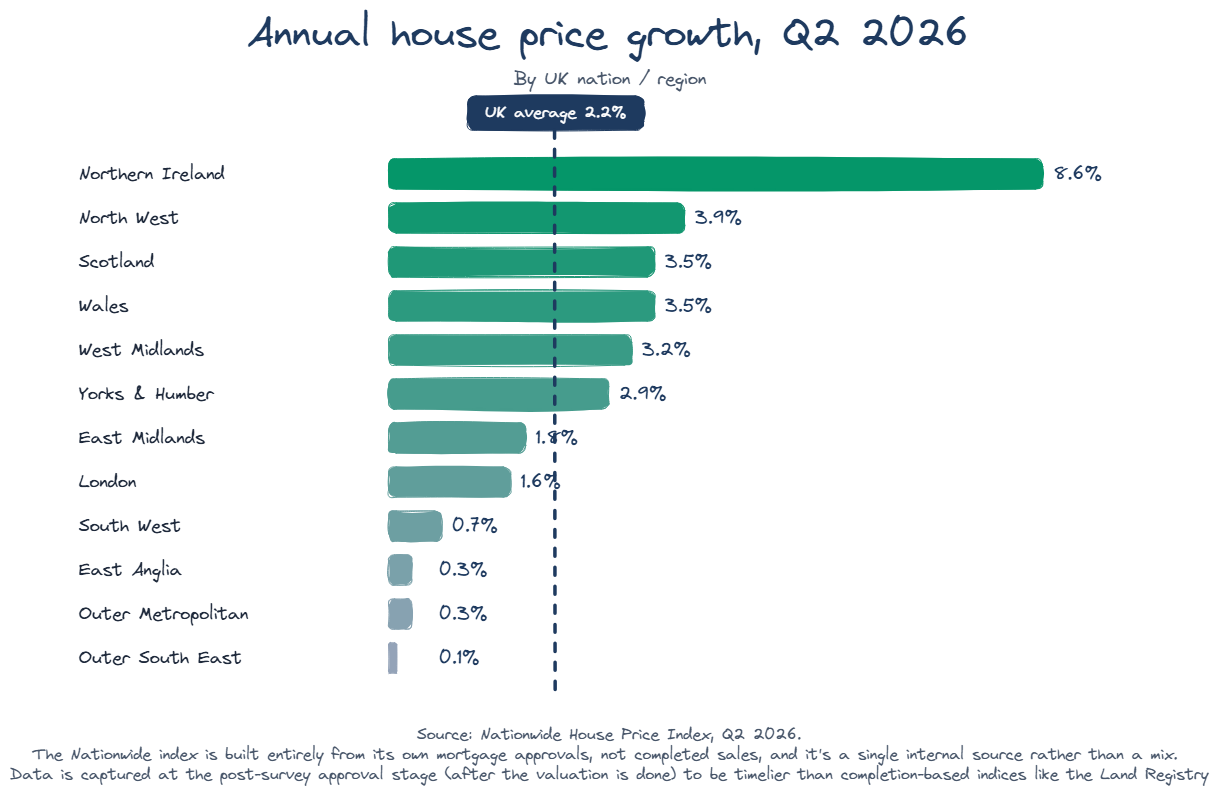
Nationwide says all 13 UK regions posted price rises in the second quarter; however, the market isn't booming or busting. It's treading water, waiting for clarity.
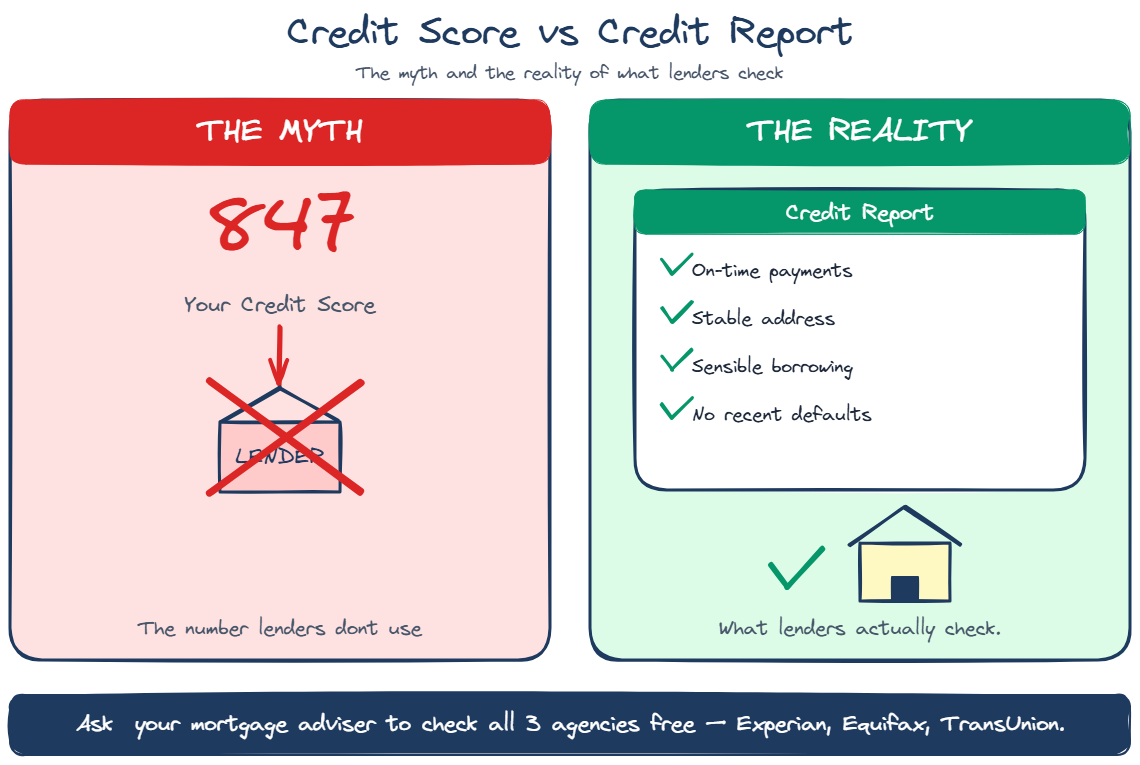
New research found that 49% of Gen Z adults worry their credit history will block them from buying a home in a survey of 2,000 UK adults aged 18 to 28.
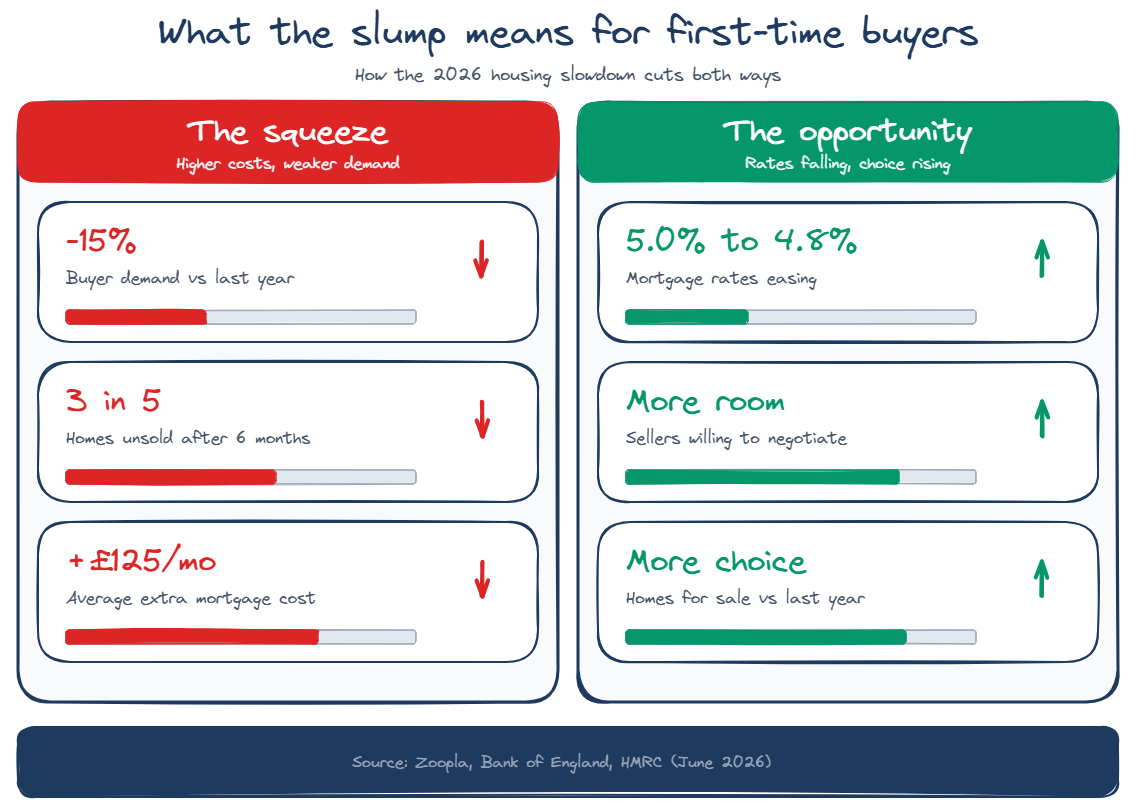
"If you are ready to move, conditions are more favourable than they were three months ago" says Zoopla
2.99% with no product fee, open to its existing TMW buy-to-let landlords
Get in touch
We are your online mortgage broker, offering you the convenience of applying for a mortgage online. However, we understand that sometimes you may prefer to speak with a human - phone, email or in person.
- Phone number
- 01133 205 902
- [email protected]
- Postal address
-
31 Bradford Chamber Business Park,
New Lane, Bradford, BD4 8BX
Looking for a career in Mortgage Advice? View job openings.
We are authorised and regulated by the Financial Conduct Authority (No. 919921). The Financial Conduct Authority does not regulate most Buy to Let mortgages.
Think carefully before securing other debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage.
Our initial consultation is free. If you choose to proceed, we’ll explain any broker fees upfront before you commit.
Cyborg Finance Limited is registered in England and Wales (No. 12131863) at Bradford Chamber, New Lane, Bradford, BD4 8BX.